After the regional banking crisis, banks tightened their lending standards again, pushing more small and medium-sized businesses toward private credit lenders.
Middle-market companies (generally those with annual revenues between $10 million and $1 billion) are frequently too small to tap the public bond market, so they’ve historically turned first to commercial banks for debt financing. With traditional lenders applying stricter standards at a time when many businesses are still recovering from COVID-era disruptions, inflation, and a tight labor market, private credit has become a viable alternative worth understanding.
In our last article, we discussed the rise of private credit and the role it’s playing in the marketplace. This article focuses on the steps involved in private credit for business owners considering it as a funding source. We’re not promoting private credit here—we’re educating you on this financing alternative so you can weigh the pros and cons and decide whether it fits your business.
How to Navigate the Private Credit Market Successfully
While the private credit market may have operated in the shadows for some time, its significance has grown exponentially over the past decade. This alternative financing landscape, driven by non-traditional lenders, has attracted a diverse array of participants seeking unique credit opportunities and tailored financial solutions.
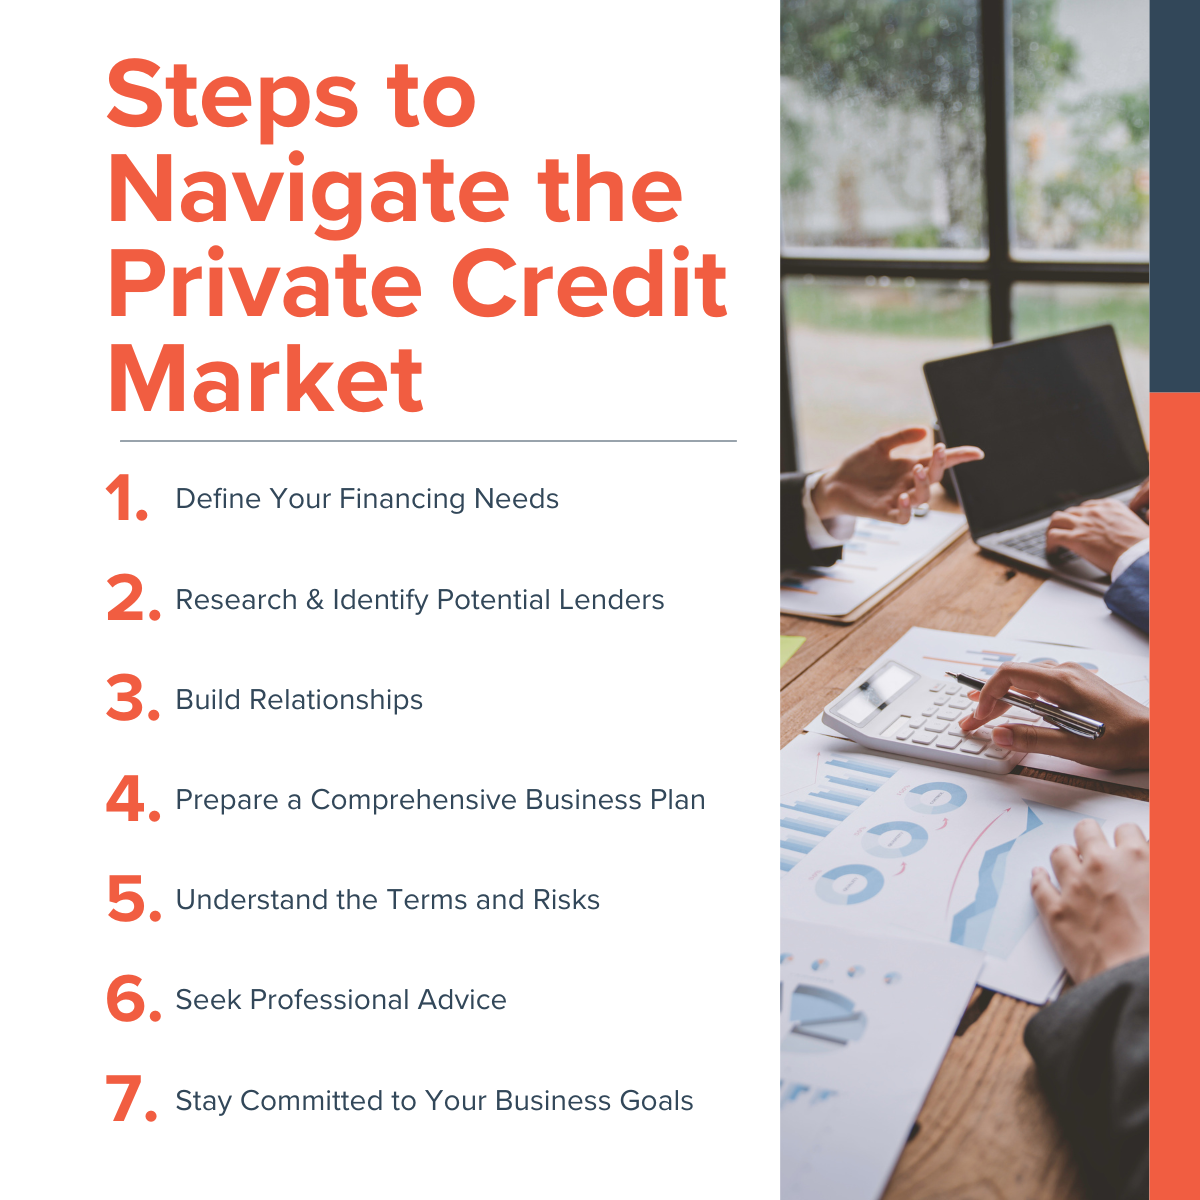
Approaching the private credit market requires careful consideration and a well-thought-out strategy. This alternative financing avenue offers borrowers unique options, but it also comes with its own set of challenges. Here are seven essential steps to guide you in navigating the private credit market successfully:
1. Define Your Financing Needs
Before entering the private credit market, clearly define your financing needs and objectives. Assess how much capital you require, the purpose of the funds, your collateral position, and the desired terms for the loan. Understanding your financial needs will help you target the right private credit lenders who can offer customized solutions.
2. Research and Identify Potential Lenders
Research is key to identifying reputable and reliable private credit lenders. Look for firms with a solid track record of successful lending and a good reputation in the industry. Consider the types of companies and industries they usually lend to, to ensure they align with your business model and goals. If they have experience lending to businesses like yours, they’re more likely to understand the nuances of your business and the customers you serve. The key is to find a value-added partner, not just someone who will loan you money.
3. Build Relationships
Establishing strong relationships is crucial in the private credit market. Similar to traditional lenders, private credit lenders prioritize relationships with borrowers. Attend industry events, networking functions, and conferences to connect with potential lenders. Building rapport and showcasing your company’s potential can enhance your chances of securing funding.
What if you don’t have time for this, or you don’t know where to start? This is where a private credit advisor can help. Many advisors who specialize in capital sourcing have in-depth knowledge of the private credit market, including its intricacies, trends, and key players. They can provide insight into the lending options available, the types of deals that are common, and typical terms and conditions, allowing you to make more informed decisions when approaching potential lenders.
4. Prepare a Comprehensive Business Plan
To gain the confidence of private credit lenders, or any lender, present a comprehensive and well-thought-out business plan. Include detailed financial projections, a clear explanation of how you intend to use the funds, and the steps you’ll take to ensure timely repayment. A robust business plan demonstrates your professionalism and commitment to the success of your venture.
Honesty and transparency are essential when dealing with any lender, including private credit lenders. Provide accurate and up-to-date financial information and be forthright about any challenges your business may be facing. Demonstrating openness will help build trust with potential lenders.
If your business is going through a period of stress or distress, your turnaround plan is your business plan. Everything above still applies—build trust through open, honest communication, and make sure your lender understands where your business is in its life cycle.
5. Understand the Terms and Risks
Carefully review and understand the terms of the loan, including interest rates, fees, prepayment penalties, repayment schedules, reporting requirements, and any covenants attached to the financing. Private credit loans often come with higher interest rates and less favorable terms than traditional bank loans, so it’s worth going in with specific questions, including:
- What happens if you trip a covenant, even temporarily?
- How is the loan’s value determined, and how often?
- What’s the lender’s track record with borrowers who hit a rough patch—do they work with you, or move quickly to enforce remedies?
- Are there prepayment penalties if your business’s circumstances change and you want to refinance?
These aren’t just fine-print details—they’re the difference between a lender who’s a genuine partner and one who simply extended you capital.
6. Work With a Private Credit Advisor
The private credit market offers unique financing opportunities for business owners seeking solutions beyond traditional bank lending, but the market’s terms and structures aren’t always intuitive if you haven’t navigated it before. A private credit advisor can help you tap into their expertise, gain access to a network of lenders, and get personalized guidance throughout the process, positioning your business for success and helping you secure funding that actually aligns with your long-term goals.
Here’s how they typically help:
- Assistance with Due Diligence: An advisor can help you navigate the due diligence process, assisting with documentation, financial statements, and other materials lenders require, so your loan application presents your business in the best possible light.
- Negotiating Favorable Terms: Advisors are skilled negotiators who can advocate on your behalf, helping negotiate interest rates, repayment schedules, and covenants that align with your long-term goals and cash flow capabilities.
- Risk Management: Entering the private credit market involves real risk, and an advisor can help you understand and manage it, identifying potential pitfalls and advising on mitigation strategies to protect your business.
- Efficient and Timely Process: Navigating the private credit market can be time-consuming and complex. Engaging an advisor can streamline the process, helping you meet deadlines, make informed decisions, and avoid pitfalls that could delay or jeopardize your financing.
7. Stay Committed to Your Business Goals
Finally, demonstrate your commitment to the success of your business. Private credit lenders are more likely to lend to companies with a clear vision, a strong management team, and a solid strategy for growth and profitability.
Private credit might be right for your business, but successfully navigating it requires a well-prepared and thoughtful approach, with clear eyes about both the opportunity and the risk. Getting private credit for business owners right starts with these seven steps—take them seriously, and you’ll be positioned to make a sound decision about whether it’s the right path for your business goals.
Ready to Talk to a Private Credit Advisor?
If you’re interested in private credit but still unsure whether you’re prepared to navigate the process, JACO’s experienced team can help. Contact us so we can learn more about your business and what you’re looking to achieve.
About Jeff
Jeff has over 30 years of strategic planning, business development, and business transformation leadership experience. Having worked with mid-market, closely-held and family-owned businesses his entire career Jeff has a unique understanding of how these enterprises operate and the challenges they face.
He is passionate about working with business leaders to build strong cultures while developing and executing strategies that deliver exceptional results that benefit all the company’s stakeholders. Jeff’s hands-on approach to working with companies begins with a commonsense approach to strategy development.
With extensive experience in organizational turnaround and growth Jeff follows a defined process (disciplined, focused, intentional) to guide clients from strategy to execution. His experience covers a multitude of industries, with an in-depth understanding of automotive manufacturing.
Jeff holds a Master’s in Business Administration from the Capital University School of Management and earned a Bachelor of Arts in Business Administration and Management from Ohio Dominican University.
He is a Certified Turnaround Professional (CPT) by the Turnaround Management Association and is a Certified Exit Planning Advisor (CEPA) by the Exit Planning Institute.